Your bank’s refusal to fund your expansion isn’t a reflection of your company’s value, but rather a symptom of an outdated underwriting model that prioritizes rigid ratios over real-world cash flow. If you’ve felt the sting of a slow approval cycle or excessive collateral demands, you know that traditional institutions often act as anchors rather than engines. The sophisticated world of commercial financing without bank involvement has become a primary choice for high-growth firms that value agility. If your current lender can’t keep pace with your opportunities, then it’s time to look toward non-bank alternatives that offer the precision your operations require.
We agree that waiting months for a “maybe” is a risk your business cannot afford in 2026. This article promises to reveal how you can bypass these bureaucratic hurdles by leveraging strategic tools like asset-based financing and sale-leasebacks. You’ll gain a clear understanding of how flexible underwriting can turn your existing assets into immediate liquidity. We will debunk the five most persistent myths about alternative capital to provide you with a strategic roadmap for securing high-leverage funds through a partner who understands complex cash flow as well as you do.
Key Takeaways
- Reframe your understanding of private capital as a strategic maneuver for agility rather than a last-resort fallback. It’s about speed, not desperation.
- Discover why non-bank lenders prioritize asset value over rigid debt-to-income ratios to accelerate your funding timeline significantly.
- Calculate the hidden cost of “cheap” bank debt by analyzing the lost revenue from missed growth opportunities and slow approval cycles.
- Follow a two-step audit-ready framework to ensure your financials meet the specific underwriting standards of private institutional investors in 2026.
- Learn how to secure commercial financing without bank limitations so you don’t let bureaucracy hold your momentum back.
Myth #1: Non-Bank Commercial Financing is a “Last Resort”
The perception that non-bank capital is reserved for distressed companies is a relic of the past. Today, private capital serves as a primary fuel source for the most aggressive growth strategies in the market. Non-bank financing is defined as capital sourced from institutional investors, private credit funds, and specialized firms that operate outside the traditional depository banking system. While banks are bound by rigid regulatory caps and slow committee approvals, these private entities prioritize the underlying value of a deal. This shift allows for a level of precision that traditional lenders simply cannot match.
If you view Alternative finance only as a fallback for a bank rejection, you’re missing a significant competitive advantage. Healthy, profitable firms frequently choose this route because they recognize that speed is a currency. In a market where a prime acquisition or a bulk inventory discount can vanish in a week, waiting 90 to 120 days for a traditional bank approval represents a massive opportunity cost. If the profit margin on a new contract exceeds the cost of capital, then the speed of execution becomes more important than the interest rate. Choosing commercial financing without bank involvement means you’re prioritizing the window of opportunity over the comfort of a local branch. It’s a proactive decision to maintain momentum when the traditional system is designed to slow you down.
The Strategic Shift to Private Capital
Fortune 500 companies and mid-market leaders don’t just use private debt because they have to; they use it because it’s efficient. Unlike banks that fixate on historical credit snapshots, non-bank lenders look forward at asset value and projected cash flow. This forward-looking approach is essential for firms undergoing rapid transformation or entering new markets. Securing commercial financing without bank restrictions ensures that non-bank financing is a tool for capital agility rather than a credit compromise. It bridges the gap between your current capacity and your future potential without the bureaucratic friction that stalls progress.
Asset-Based Financing as a Growth Engine
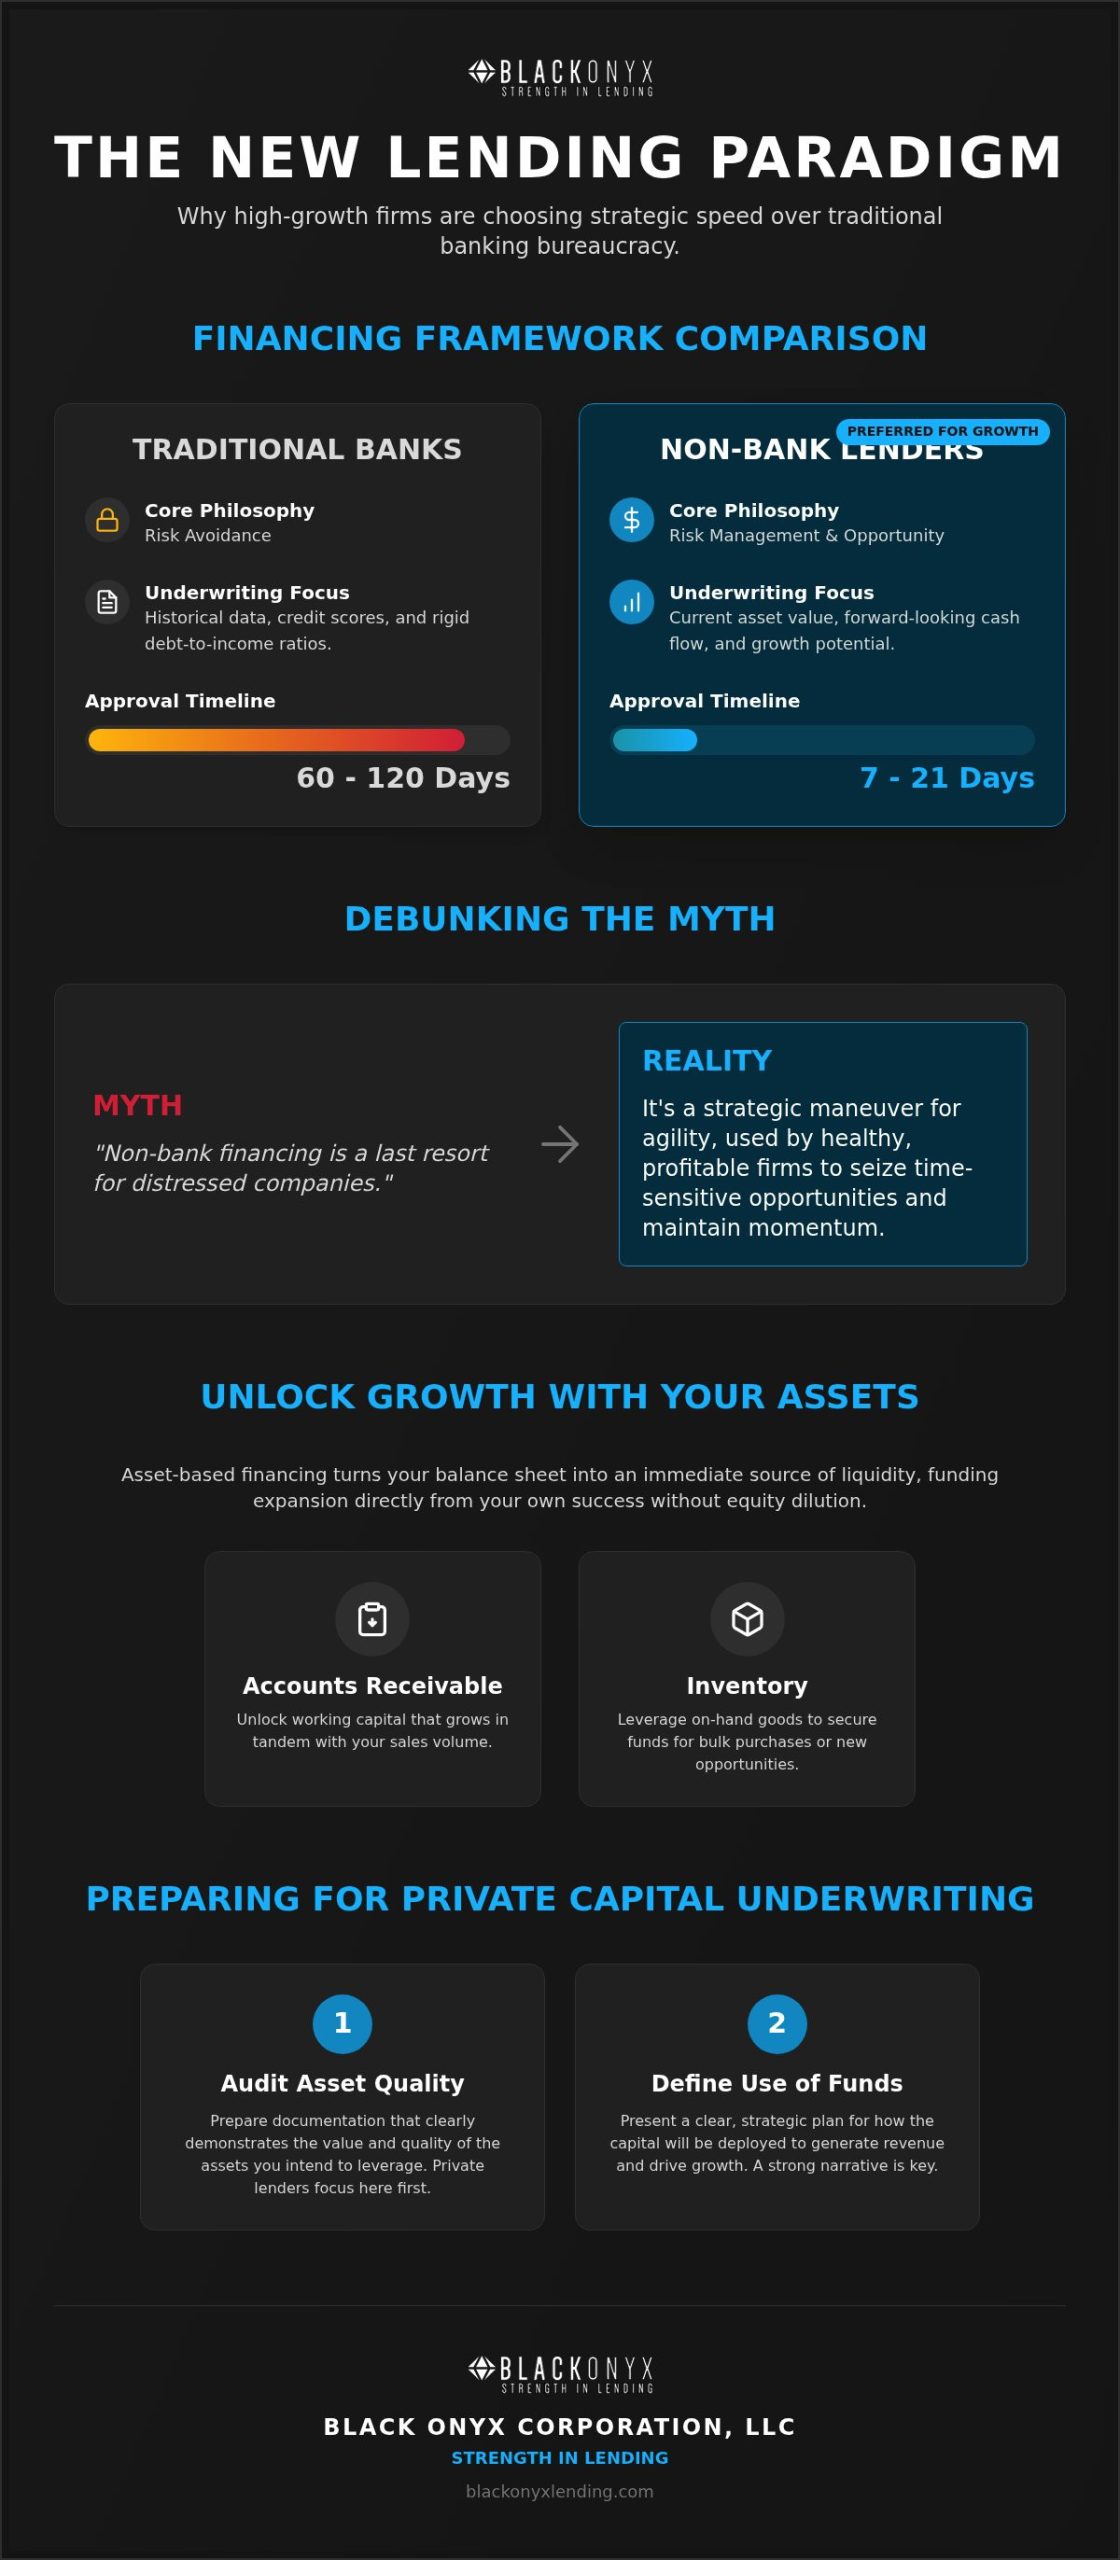
Scaling a business requires liquidity that traditional debt-to-income ratios often restrict. By leveraging accounts receivable and inventory, you can unlock immediate working capital that grows in tandem with your sales volume. This is the core benefit of asset based financing. It supports rapid scaling without forcing you into equity dilution or restrictive bank covenants. Using your balance sheet as a growth engine ensures that your expansion is funded by your own success. If your growth is outpacing your bank’s comfort level, these asset-centric tools provide the necessary runway to capture market share quickly.
Comparing the Framework: Traditional Banks vs. Non-Bank Lenders
Traditional banks operate on a philosophy of risk avoidance, whereas non-bank lenders operate on a philosophy of risk management. This fundamental difference dictates how each entity views your balance sheet. A bank typically analyzes debt-to-income ratios and historical cash flow to ensure you can survive a downturn. Conversely, private lenders prioritize asset value, focusing on what you own today to fuel what you’ll earn tomorrow. This shift in perspective allows for a much faster execution. While a bank might take 60 to 120 days to navigate multiple committees, a non-bank structure can often close in 7 to 21 days.
Legitimate non-bank options are increasingly supported by federal initiatives, such as the U.S. Treasury Small Business Programs, which have expanded the availability of private credit. This ecosystem provides the speed necessary to capture time-sensitive deals. If you’re pursuing commercial financing without bank constraints, you’re choosing a partner that values your current collateral over your three-year-old tax returns.
Underwriting: Credit Scores vs. Asset Quality
Banks traditionally lean on “The Five Cs” of credit, requiring perfection in character, capacity, capital, collateral, and conditions. Private lenders, however, often distill their focus down to asset quality and the specific use of funds. This is where professional commercial underwriting consulting becomes critical. A consultant helps you present your assets in a language that private institutional investors prefer. They act as a strategic bridge, ensuring your application highlights strength rather than highlighting bureaucratic deficiencies.
Consider a real-world scenario. A manufacturing firm might have a 600 FICO score due to a previous personal medical crisis, which would trigger an automatic rejection at any major bank. However, if that same firm holds $2 million in creditworthy accounts receivable, a non-bank lender sees a low-risk opportunity to provide liquidity. The focus shifts from a flawed personal history to a robust corporate asset. If your balance sheet is strong but your credit report is noisy, securing commercial financing without bank interference is often the only logical path forward.
The Flexibility Factor in Loan Structures
Private debt offers a level of customization that a standardized bank loan cannot replicate. If your business is seasonal, a private lender can structure a repayment schedule that aligns with your peak revenue months. You might secure an interest-only period during a heavy equipment installation phase to preserve working capital. These customized covenants don’t stifle your operational growth with rigid reporting requirements. If you meet your milestones, then your lender remains a silent, supportive partner. This “if-then” flexibility allows you to manage your cash flow based on reality rather than a generic bank policy. To determine which structure fits your specific growth phase, you can speak with a strategic consultant to explore your current funding potential.
Myth #2: Private Financing is Prohibitively Expensive
Focusing solely on the annual percentage rate (APR) is a common trap that obscures the true value of a deal. While a traditional bank might offer the lowest headline rate, that number doesn’t account for the hidden costs of delays, restrictive covenants, and lost revenue. If you’re comparing commercial financing without bank involvement to a traditional loan, you must look at the total cost of capital. A higher rate on a short-term bridge is often far more profitable than a low rate on a loan that takes four months to close. To better understand the landscape, it’s useful to define What is a nonbank and why these institutions charge for the speed and risk they absorb on your behalf.
The price of capital is only one side of the equation; the other side is the return on that capital. If a bank’s slow approval process causes you to miss a bulk inventory discount or a time-sensitive acquisition, the “savings” on interest are irrelevant. Private lenders provide the liquidity required to act decisively. When you move away from the bank model, you’re paying for a level of certainty and execution that traditional institutions aren’t built to provide.
The ROI of Speed and Certainty
Speed is a competitive advantage that has a quantifiable dollar value. If a purchase order requires $200,000 in raw materials to fulfill a $500,000 contract, waiting sixty days for a bank “yes” could mean losing the contract entirely. In this scenario, the interest paid to a private lender is a small fraction of the profit you’d otherwise forfeit. Utilizing accounts receivable financing allows you to bridge these gaps without missing a beat. It eliminates the payroll stress that often accompanies rapid growth phases. The cheapest money is the money that arrives in time to capture the opportunity.
Tax Efficiency: Leasing and Section 179
The headline interest rate also fails to account for the significant tax advantages of non-bank structures. When you choose commercial equipment leasing, your payments are often treated as fully deductible operating expenses rather than just interest deductions. This can drastically reduce your effective after-tax cost of capital compared to a traditional bank loan. Additionally, a Sale-Leaseback can unlock dormant capital trapped in your existing assets without adding new debt to your balance sheet. If you calculate the net impact on your bottom line, the “expensive” private option often becomes the most fiscally responsible choice for a growing firm.
Audit-Ready: Preparing for Non-Bank Underwriting in 2026
Securing commercial financing without bank involvement requires a pivot in how you present your firm’s value. While a bank wants to see three years of stable tax returns, a private underwriter wants to see your current velocity. Preparation isn’t about hiding flaws; it’s about highlighting the assets that represent immediate collateral. To position your business for a rapid approval, you must follow a methodical readiness framework:
- Step 1: Organize Asset Aging Reports. Compile detailed accounts receivable and inventory reports. Non-bank lenders prioritize the quality of your customers and the liquidity of your stock over your personal credit score.
- Step 2: Develop a “Use of Funds” Statement. Clearly articulate how the capital will generate a return. Underwriters are more likely to approve a deal when they see that $500,000 in financing will fulfill a contract worth $1.2 million.
- Step 3: Clean Internal Financial Reporting. Ensure your profit and loss statements are current and transparent. Professionalism in your reporting reflects the quality of your management.
- Step 4: Engage a Strategic Consultant. Navigating a global network of over 100 funding sources is a massive undertaking. A consultant acts as a filter, matching your specific asset profile to the right institutional investor.
The Power of the Narrative
Private lenders buy into the story of your business, not just the spreadsheet. They want to know why your growth is accelerating and how their capital serves as the missing piece of the puzzle. This is where personalized business loan consulting becomes your greatest asset. A consultant helps you refine your narrative to address the specific concerns of non-bank underwriters. They prioritize documentation like purchase orders, master service agreements, and equipment appraisals over historical tax snapshots. If you can prove the future profitability of the deal, then the past becomes secondary.
Leveraging Professional Underwriting
One of the most significant advantages of working outside the traditional banking system is the ability to pre-underwrite your own deal. A professional consultant identifies potential red flags, such as economic obsolescence in your equipment valuations, before the formal submission. If your machinery is physically sound but technologically outdated, a strategic consultant knows how to frame its value to the right niche lender. This proactive approach prevents the “single point of failure” risk associated with traditional bank applications. By accessing multiple funding sources simultaneously, you ensure that your momentum is never at the mercy of a single committee’s opinion. To begin your readiness assessment and explore your options, connect with our strategic consulting team today.
Securing Your Future with Black Onyx Strategic Financing
Breaking your dependency on traditional lenders isn’t just about finding a new source of funds. It’s about a fundamental shift in your corporate DNA. Moving toward a capital-independent model ensures that your growth is dictated by your performance, not a bank’s shifting risk appetite. When you leverage commercial financing without bank constraints, you’re choosing a path where assets lead and bureaucracy follows. Black Onyx Corporation, LLC exists to facilitate this transition by acting as a seasoned consultant and a strategic bridge to a global network of resources. We don’t just provide capital; we provide the momentum needed to move from a state of limitation to one of significant opportunity.
Our network provides access to over 100 funding sources, but our value lies in the precision of our matches. Our expertise spans across the US, Canada, Australia, and the UK, giving you a reach that local banks simply cannot duplicate. We don’t just submit applications; we engineer approvals. By prioritizing a professional underwriting process upfront, we remove the obstacles that typically cause delays in the private market. If you want to scale with confidence in a complex 2026 market, then you need a partner who understands that speed and structure are just as important as the capital itself.
The Black Onyx Advantage: Beyond Brokerage
Our approach is rooted in the belief that every business deal is a unique narrative. We act as a high-level consultant, translating your operational success into a language that institutional investors respect. This is especially critical in highly specialized sectors. For example, our expertise in medical equipment financing allows us to navigate the specific regulatory and technical nuances of that industry. Because we understand the equipment’s value and the provider’s cash flow, we can secure terms that generalist lenders would overlook. Our underwriting-first philosophy ensures that when we present a deal to our network, it’s already structured for success, leading to significantly higher closing rates.
Next Steps for Your Commercial Capital Strategy
The transition from limitation to opportunity begins with a preliminary underwriting consultation. During the first 48 hours of engagement, we conduct a deep dive into your asset aging reports and your specific “Use of Funds” statement. We identify the most viable pathways to liquidity and match your needs with the most aggressive funding sources in our network. This methodical approach respects your time and protects your business from the “rejection fatigue” common in the banking world. If you’re ready to transform your balance sheet into a high-leverage growth engine, then the time for action is now. Speak with a Black Onyx Strategist Today to unlock the capital your business deserves.
Master Your Capital Independence in 2026
The transition from bank-dependent stagnation to capital-independent growth requires a fundamental shift in how you view your balance sheet. We’ve established that speed is a quantifiable currency and that your current assets hold more strategic value than a historical credit snapshot. Securing commercial financing without bank interference is no longer a fallback strategy; it’s a sophisticated maneuver for firms that refuse to let bureaucracy dictate their expansion. By focusing on your future cash flow and leveraging professional underwriting, you can unlock liquidity that traditional institutions simply aren’t built to provide.
Black Onyx Corporation, LLC offers the specialized underwriting expertise and global reach across the US, Canada, UK, and Australia needed to navigate this landscape. With access to over 100 funding sources, we ensure your deal is matched with the right institutional capital. If you’re ready to bypass the committee and fuel your next growth phase, it’s time to act. Schedule Your Strategic Underwriting Consultation today and start building the momentum your business deserves. Your next level of scale is within reach.
Frequently Asked Questions
Is commercial financing without a bank safe for my business?
Non-bank financing is a secure and legitimate alternative when you partner with established institutional investors and specialized capital firms. Modern private credit operates with high levels of contractual transparency and professional oversight. If you utilize a consultant to vet these sources, you ensure that the terms are fair and the lender is reputable. It’s a strategic way to diversify your capital sources beyond a single institution while maintaining professional standards.
How much more does non-bank financing cost compared to a traditional bank?
While the annual percentage rate for non-bank capital is typically higher than a prime bank rate, the total cost of capital often favors the private route. If a bank’s delay causes you to miss a significant profit opportunity, then the “cheaper” loan actually costs you more. You’re paying for speed, flexibility, and certainty of execution. When you calculate the net profit generated by the capital, the ROI frequently justifies the interest gap.
Can I get a commercial loan without a bank if I have a low credit score?
You can secure commercial financing without bank limitations even with a low personal credit score because private lenders prioritize asset value over historical snapshots. If your business holds quality accounts receivable, inventory, or equipment, these assets act as the primary collateral for the loan. This shift from credit-centric to asset-centric underwriting allows profitable companies with past financial noise to access the liquidity they need for immediate growth.
What is the fastest way to get commercial financing without a bank?
The fastest route to liquidity is typically through accounts receivable financing or purchase order funding. These structures allow you to bypass the lengthy committee reviews required by traditional lenders. If your documentation is organized, you can often secure funding in as little as 7 to 21 days. This speed allows you to respond to market shifts or inventory demands that would otherwise be lost during a typical 90-day bank approval cycle.
What assets can I use for non-bank commercial financing?
You can leverage a wide range of corporate assets to secure capital. Common examples include:
- Accounts receivable from creditworthy customers
- Marketable inventory and raw materials
- Commercial equipment and machinery
- Real estate through sale-leaseback arrangements
By using these tangible assets, you transform dormant value on your balance sheet into active working capital without the need for traditional debt structures.
Do non-bank lenders require personal guarantees like banks do?
Non-bank lenders often provide more flexibility regarding personal guarantees compared to traditional banks. If the underlying asset value is strong enough to cover the risk, some private lenders may waive or limit the scope of personal liability. This is a significant advantage for business owners who wish to separate their personal net worth from their corporate obligations. Requirements vary based on the specific funding source and the complexity of the deal.
What happens if my business is located outside the United States?
If your business operates outside the United States, you can still access high-leverage capital through our global network. Black Onyx Corporation, LLC maintains strategic partnerships with funding sources in Canada, the United Kingdom, and Australia. This international reach ensures that your expansion isn’t restricted by geography. We help you navigate the specific financial nuances of these markets while maintaining the same speed and professional underwriting standards we provide to our domestic clients.
How do I know which non-bank lender is right for my specific industry?
The most efficient way to identify the right lender is to engage a strategic consultant who manages a vast network of specialized sources. Different lenders have specific appetites for industries like medical, manufacturing, or logistics. If you try to navigate commercial financing without bank help alone, you risk wasting time with firms that don’t understand your niche. A professional consultant matches your unique asset profile with lenders who have a proven track record in your sector.