A bank rejection letter isn’t a final verdict on your company’s viability; it’s often just a symptom of a rigid, automated system that cannot translate your unique operational strengths into a checkbox. If you’ve spent weeks managing multiple applications only to be met with silence or confusing, predatory terms, you know that the traditional lending path is increasingly broken. In 2026, securing the right capital requires more than a standard application. It demands personalized business loan consulting that transforms your financial narrative into a high-grade investment prospect. You deserve a strategic partner who replaces bureaucratic obstacles with a clear path to momentum.
We understand the frustration of being labeled non-bankable despite having a growing enterprise. This article demonstrates how expert underwriting and a global network of over 100 lenders can bridge the gap between a rejected file and strategic funding. You’ll discover how to fix your financial profile and access a curated list of funding sources, from SBA loans to asset-based financing, that support long-term growth rather than just short-term survival. We will break down the precise steps to move from a state of limitation to one of significant opportunity by aligning your unique assets with the right strategic capital.
Key Takeaways
- Learn why a high-level consultant acts as your strategic advocate, navigating 2026 market volatility more effectively than any automated lending portal.
- Discover how personalized business loan consulting utilizes a pre-underwriting phase to identify and resolve financial red flags before they reach a lender.
- Compare the restrictive credit boxes of traditional banks with the expansive, global funding networks that prioritize your business’s long-term growth.
- Understand the deep-dive diagnostic process that transforms your existing assets into powerful leverage for securing competitive financing terms.
- Learn how to bridge the gap between your current capital limitations and a network of 100+ global lenders through expert negotiation and deal structuring.
What is Personalized Business Loan Consulting and Why is it Essential in 2026?
The gap between a business owner and the capital they need has widened in 2026, despite the proliferation of digital lending portals. While these platforms promise speed, they often lack the nuance required for complex commercial needs. This is where personalized business loan consulting becomes indispensable. A consultant isn’t a mere intermediary; they’re a strategic advocate who understands that your balance sheet is a narrative, not just a spreadsheet. They don’t just find a loan; they engineer a capital solution that aligns with your specific operational goals.
The broader field of commercial finance has shifted toward a model where those who rely solely on traditional bank channels face increasing “economic obsolescence.” With the bank prime rate sitting at 6.75% as of September 2026, the cost of capital is too high to waste on sub-optimal structures. A consultant looks beyond the simple act of borrowing to help you optimize your entire capital structure. This ensures every dollar supports a specific competitive advantage rather than just filling a temporary hole in cash flow.
The Human Element vs. The Algorithm
Algorithms prioritize historical data. This often penalizes high-growth companies or those navigating temporary industry shifts. If your business doesn’t fit the “standard” credit box, an automated portal will trigger a rejection without explanation. A personalized consultant acts as a strategic bridge. They translate your operational potential into a risk story that global lenders can support. They identify hidden liquidity in equipment, real estate, or accounts receivable that an algorithm might completely ignore. It’s about moving from a state of limitation to one of significant opportunity through expert advocacy.
Identifying Strategic Growth Opportunities
Growth in 2026 requires looking past simple working capital to long-term asset-based strategies. This might include sale-leaseback financing, where you unlock equity from owned real estate to fund expansion without incurring traditional debt. By aligning loan terms with your specific cash flow cycles, a consultant ensures your financing supports momentum. This proactive approach turns personalized business loan consulting into a tool for transformation. If you want to scale, you need a capital structure that breathes with your business, not one that suffocates it with rigid repayment terms.
How Does Professional Underwriting Consulting Improve Your Approval Odds?
Most lenders use automated filters to weed out applications instantly. If you submit a file with unresolved red flags, you’re likely to face an immediate rejection that damages your credit profile. Personalized business loan consulting introduces a critical “pre-underwriting” phase. This proactive step involves identifying and fixing financial discrepancies before a lender ever sees your file. By cleaning up your balance sheet and addressing debt-to-income ratios early, you present a polished, low-risk profile that aligns with specific lender requirements.
Shotgunning applications to dozens of banks is a common mistake that signals desperation and lowers your credit score. Instead, we structure the deal to meet the specific criteria of niche commercial lenders. For example, as of September 2026, new SBA rules require businesses to be 100% owned by U.S. citizens for certain programs. A consultant ensures your ownership structure and financial story are verified and compliant before submission. We don’t just ask for money; we negotiate covenants and terms that favor your operational flexibility, ensuring the loan doesn’t become a burden as you scale.
The Underwriting Readiness Checklist
In 2026, a basic balance sheet isn’t enough to secure competitive rates. Lenders now demand deeper insights into cash flow coverage and debt service coverage ratios (DSCR). A DSCR of 1.25 or higher is generally preferred by traditional institutions, though niche players may offer more leeway if the asset base is strong. Engaging in commercial underwriting consulting prevents application rejection by identifying documentation gaps and financial weaknesses that would otherwise trigger an automated decline. If you present your cash flow effectively from the start, you eliminate the friction that typically slows down the approval process.
Negotiating with Leverage
Capital is a commodity, and you should treat it as such. By leveraging a network of over 100 funding sources, we create a competitive environment where lenders must bid for your business. This competition is the primary driver for lowering interest rates and extending repayment terms. Whether you’re exploring SBA loan programs or private asset-based solutions, professional negotiation ensures you aren’t stuck with “off-the-shelf” terms. This is especially vital given the bank prime rate of 6.75% in late 2026; even a half-point reduction in your spread can save thousands over the life of the loan.
Our role as a strategic bridge means we manage the entire closing process, ensuring speed and precision. If you want to see how these strategies apply to your specific situation, you can explore our advisory services to begin your financial diagnostic. This focused oversight allows you to stay concentrated on running your business while we handle the complexities of the capital market.
Personalized Consulting vs. Traditional Bank Applications: A 2026 Comparison
Local banks typically operate within a narrow “credit box.” If your debt-to-income ratio is slightly off or your industry is currently flagged as high risk, you’re rejected. Personalized business loan consulting provides access to a global network of over 100 lenders with diverse risk appetites. While a local bank might take weeks to move an application through a committee, a consultant bypasses these gatekeepers by going directly to the decision-makers. This speed is critical when you’re trying to capture a market opportunity or manage a sudden growth spike.
For businesses with high-quality invoices but low cash on hand, accounts receivable financing offers a way to bridge the gap without taking on traditional debt. This product is often overlooked by local branches that prefer standard term loans. A consultant identifies these “non-bankable” deals and structures them for success. The difference in success rates is stark; where a bank sees a risk, a strategic consultant sees a structured opportunity.
When the Bank Says No: Alternative Paths
Asset-based lending bypasses traditional credit score hurdles by focusing on the underlying value of your collateral. This allows companies with complex histories to secure funding that a traditional bank would never approve. Purchase order financing is another powerful tool. It lets you fulfill large contracts by using the purchase order itself as leverage, effectively funding your supply chain without bank debt. Additionally, leveraging equipment leasing preserves your cash flow and avoids the risk of technical obsolescence. High-growth firms that need to move quickly are increasingly turning to commercial financing without bank involvement to access these flexible, asset-driven solutions. While you might explore small business grants and programs to supplement your capital, these strategic debt instruments provide the immediate liquidity needed for scaling.
SBA Loans: The Strategic Route
Applying for an SBA loan directly through a bank is often a gamble. Banks frequently add their own “overlays” to SBA rules, making approval significantly harder than the government requires. Working with an SBA loan consultant ensures you navigate the complexities of 7(a) and 504 programs with expert precision. As of July 4, 2026, the SBA separated borrowing limits for these programs. This allows a business to access up to $5 million from each, for a combined total of $10 million. A consultant helps you maximize these amounts while structuring the deal to minimize personal guarantee exposure, protecting your private assets while fueling corporate growth.
What Should You Expect During the Business Loan Consulting Process?
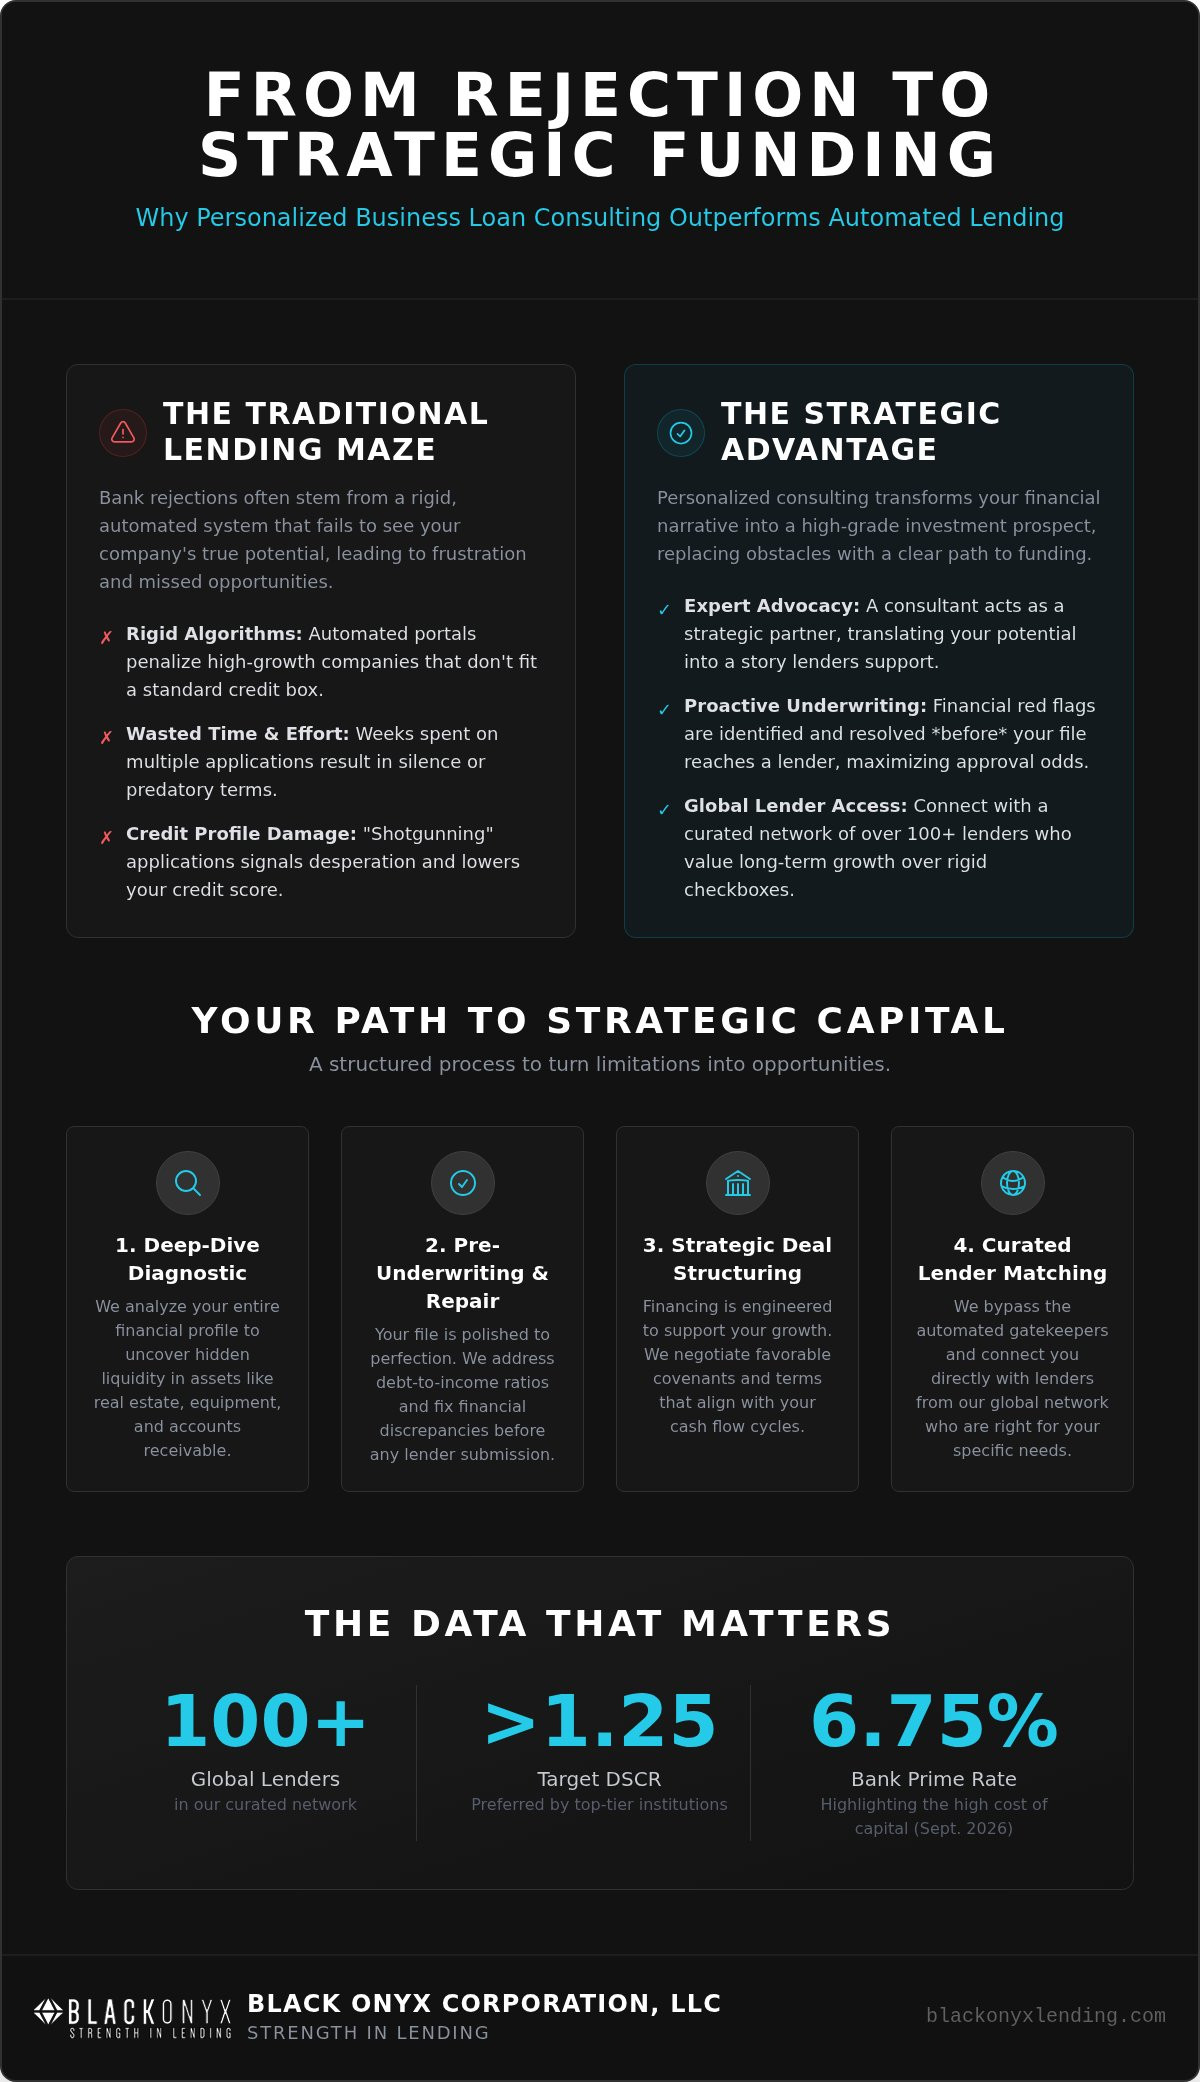
Engagement begins with a rigorous framework designed to move your business from a state of limitation to one of significant opportunity. We don’t just ask how much you want to borrow. We ask what you intend to achieve. This methodology ensures that the capital you receive is a tool for transformation, not a temporary patch. By following a structured, four-phase path, personalized business loan consulting removes the guesswork and bureaucratic friction common in traditional banking.
The Discovery and Diagnostic Phase
The first stage is a deep-dive discovery where we align your strategic goals with the most efficient capital structures. Often, a client believes they need a traditional term loan when a sale-leaseback or purchase order financing arrangement would actually provide better liquidity without the same debt burden. We conduct a financial health diagnostic that looks for hidden value in your balance sheet. This includes evaluating:
- Equipment and Machinery: Assessing current market value for potential leasing or asset-based lending.
- Accounts Receivable: Identifying high-quality aging reports that can be converted into immediate cash.
- Real Estate Equity: Unlocking capital tied up in corporate-owned property.
By the end of this phase, we’ve defined an optimal capital mix specific to your industry. If you’re in manufacturing, your needs differ vastly from a medical practice or a high-volume distributor. We ensure your financial narrative is polished and ready for the global market. It’s about precision. If the diagnostic reveals a gap in your debt-to-income ratio, we fix it before the first application is ever submitted.
Lender Matching and Selection
Once the diagnostic is complete, we move into targeted lender matching. We filter through our network of 100+ global funding sources to identify the top three to five strategic fits. We don’t just send out raw data. We present a professional “Lender Memorandum” that frames your business as a high-grade investment prospect. This document professionalizes your image and preemptively answers the questions that underwriters typically ask. It creates a sense of confidence that an automated portal simply cannot replicate.
The final phase involves submission and aggressive term negotiation. We look beyond the surface interest rate to the total cost of capital, including origination fees which typically range from 0.5% to 5% in 2026. We leverage lender competition to secure favorable covenants and repayment structures that support your cash flow cycles. This proactive approach ensures you’re not just getting a loan; you’re securing a partnership that fosters long-term growth. If you are ready to see how this structured process can fix your financial file, connect with our strategic consulting team to begin your diagnostic today.
Why Partner with Black Onyx for Your Strategic Financing Needs?
Choosing a financial partner is a decision that dictates your company’s trajectory for years. At Black Onyx Corporation, LLC, we act as a strategic bridge between your immediate capital requirements and a global network of over 100 third-party funding sources. Our decades of experience in complex commercial finance allow us to see opportunities where traditional banks see risk. We don’t just facilitate transactions; we provide the personalized business loan consulting necessary to navigate a volatile 2026 market. Whether you’re operating in the US, Canada, Australia, or the UK, our team ensures your capital structure is optimized for a competitive edge.
Specialization is at the core of our success. We possess deep expertise in manufacturing and medical equipment financing, sectors where equipment obsolescence and high entry costs demand creative solutions. Our results-oriented approach focuses on removing bureaucratic obstacles that stall progress. If a traditional lender has rejected your application, we pivot toward asset-based financing or sale-leaseback strategies that leverage your company’s inherent value rather than just its credit score. For businesses ready to explore commercial financing without bank constraints, these non-traditional strategies can unlock capital that rigid institutional lenders routinely overlook. We turn financial limitations into significant opportunities through precision and persistent advocacy.
The Black Onyx Underwriting Advantage
Our headquarters in Troy, Michigan, serves as the command center for our global capital network. Every deal receives individualized attention from senior consultants who manage the entire underwriting process. This proactive mindset is what turns “denied” files into “funded” success stories. We review your financials with the same critical eye as a lender’s credit committee, fixing red flags and strengthening your risk story before submission. If your business faces complex hurdles, our specialized underwriting and negotiation services provide the leverage needed to secure favorable terms and protect your operational flexibility.
Next Steps: Securing Your Business’s Future
Momentum is a business’s most valuable asset. To maintain it, you must have reliable access to strategic capital that supports long-term growth. Initiating a confidential consultation with our team is the first step toward reclaiming control of your financial future. We recommend preparing an initial document package, including your most recent balance sheet and aging reports, for a rapid review. This allows us to provide a financial health diagnostic quickly and start the targeted lender matching process across our global network.
Capital markets in 2026 move quickly, and you need an ally who moves faster. Don’t let rigid bank criteria or confusing lending options dictate your potential. Schedule your personalized business loan consultation with Black Onyx and experience the difference that expert advocacy makes in securing the future of your enterprise.
Engineering Your Capital Strategy for 2026 and Beyond
Success in the current commercial landscape requires a shift from passive borrowing to active capital optimization. You’ve seen how professional pre-underwriting removes the red flags that trigger automated rejections; likewise, you’ve discovered how niche asset-based strategies unlock liquidity where traditional banks see only risk. By moving beyond local credit boxes, you gain the flexibility needed to scale your operations without the burden of sub-optimal debt structures. This is the core value of personalized business loan consulting: it turns your financial narrative into a high-grade investment prospect.
Black Onyx acts as your strategic bridge, leveraging an expert underwriting team and a network of over 100 funding sources. Our global reach across the US, UK, Canada, and Australia ensures that your business has access to the most competitive terms available in 2026. If you’re ready to move from a state of limitation to one of significant opportunity, our consultants are prepared to lead the way. Don’t let bureaucratic obstacles stall your momentum when strategic capital is within reach.
Secure Your Strategic Capital: Contact Black Onyx Today and take the first step toward a curated, best-fit funding solution that supports your long-term vision.
Frequently Asked Questions
What is the difference between a loan broker and a business loan consultant?
A loan broker typically acts as a transactional middleman, simply passing applications from the borrower to a lender for a commission. In contrast, personalized business loan consulting involves acting as a strategic advocate for your company. We perform deep-dive financial diagnostics and professional pre-underwriting to fix red flags before any submission occurs. This proactive approach ensures your capital structure is optimized for long-term growth rather than just immediate survival.
How much does personalized business loan consulting typically cost?
Fees for these services are structured according to the complexity of the deal and the specific advisory required. Revenue is generally generated through professional consulting fees for underwriting, loan origination fees, and commissions earned upon the successful closing of a loan or lease. Every commercial deal is unique; therefore, we provide a clear fee structure during the initial discovery phase to ensure our strategic guidance aligns with your funding goals.
Can a consultant help me if I have already been denied by my local bank?
Yes, bank rejections often result from rigid, automated credit boxes rather than a lack of business viability. We specialize in handling non-bankable deals by identifying hidden liquidity in your assets that traditional institutions overlook. If your local bank says no, we pivot toward creative solutions like sale-leaseback financing or asset-based lending. Our team bridges the gap between a rejected file and strategic funding through a network of 100+ global lenders.
How long does the consulting and funding process take in 2026?
Speed is a primary focus, but the exact timeline depends on your documentation readiness and the complexity of the financing product. Asset-based solutions or accounts receivable financing can often be structured in just a few days. More complex SBA loans or large-scale equipment leases may take several weeks. Our specialized underwriting process accelerates these timelines by ensuring your application is lender-ready the moment it reaches a decision-maker’s desk.
What types of assets can be used for asset-based financing through a consultant?
Asset-based financing leverages the tangible value within your company to secure immediate liquidity. Common assets include machinery, medical equipment, commercial real estate, and high-quality accounts receivable aging reports. We also evaluate purchase orders and inventory to provide essential working capital. By focusing on the asset’s value rather than just a credit score, we unlock capital that traditional banks typically ignore, fostering momentum for your expansion projects.
Does working with a consultant guarantee that my loan will be approved?
No professional consultant can guarantee a loan approval, as final decisions always rest with the third-party funding sources. However, personalized business loan consulting significantly improves your odds by resolving financial discrepancies during the pre-underwriting phase. We don’t submit applications that we don’t believe are viable. Our goal is to structure your deal so it meets the precise criteria of niche lenders, which maximizes your chances of a successful closing.
Is personalized consulting available for international business expansion?
Our strategic reach extends beyond the United States to include partners in Canada, Australia, and the United Kingdom. We leverage a global network of resources to support your international growth initiatives. Whether you are leasing equipment for an overseas facility or need purchase order financing for global trade, we act as a strategic bridge. This ensures your capital structure remains efficient and compliant across multiple jurisdictions while you focus on competitive scaling.
How does a consultant help with SBA loan applications specifically?
We guide you through the complexities of SBA 7(a) and 504 programs by managing the entire submission process and navigating recent regulatory updates. As of 2026, businesses must be 100% owned by U.S. citizens to be eligible for certain SBA programs. We help you verify compliance and professionalize your application to meet these strict standards. Our team works to maximize your loan amount while structuring the deal to minimize personal guarantee exposure.