Your bank’s “no” is often just a sign that your application lacked the strategic underwriting required for a complex federal program. You likely feel the weight of overwhelming paperwork and the fear that a single mistake in the 50/40/10 structure will derail your expansion in 2026. Working with an sba 504 loan consultant changes this dynamic by shifting the burden of technical compliance from your desk to a seasoned expert. It’s exhausting to manage daily operations while trying to decode lender requirements that seem to change by the month.
If you’re ready to move from a state of limitation to one of significant opportunity, expert consulting acts as the essential bridge between your vision and a successful closing. We understand that the secret to a fast approval isn’t just filling out forms; it’s about positioning your business as a low-risk opportunity for the CDC and the primary lender. This article reveals how professional management simplifies the application process, allowing you to secure a 10% down payment and long-term fixed rates that conventional loans can’t match. You’ll learn exactly how our strategic approach removes the friction from commercial real estate financing so you can focus on your company’s long-term success.
Key Takeaways
- Understand how the 50/40/10 structure leverages bank and CDC partnerships to minimize your initial capital outlay and preserve cash flow.
- Discover why the long-term, fixed-rate debentures of the 504 program offer superior stability for commercial real estate compared to variable-rate alternatives.
- Learn how an sba 504 loan consultant manages preliminary underwriting and professional business planning to bypass common bank rejections.
- Identify the critical differences between 504 and 7(a) loans to ensure you select the right vehicle for fixed asset acquisition versus working capital.
- Master the five-step consultant-led process that streamlines complex federal requirements into a manageable, results-oriented timeline.
What is an SBA 504 Loan Consultant and Why Does Your Business Need One?
An sba 504 loan consultant is a professional advisor who meticulously structures commercial real estate deals to align with the rigid requirements of the Small Business Administration, Certified Development Companies (CDCs), and private lending institutions. While many business owners assume their local bank is the final authority on financing, the reality is that traditional lenders often have limited appetites for specific industries or risk profiles. In 2026, where market dynamics demand precision, a consultant acts as your strategic advocate. They transform a complex financial request into a high-probability approval by identifying the right lending partners before you ever submit an application.
The 504 Loan Structure: 50/40/10 Explained
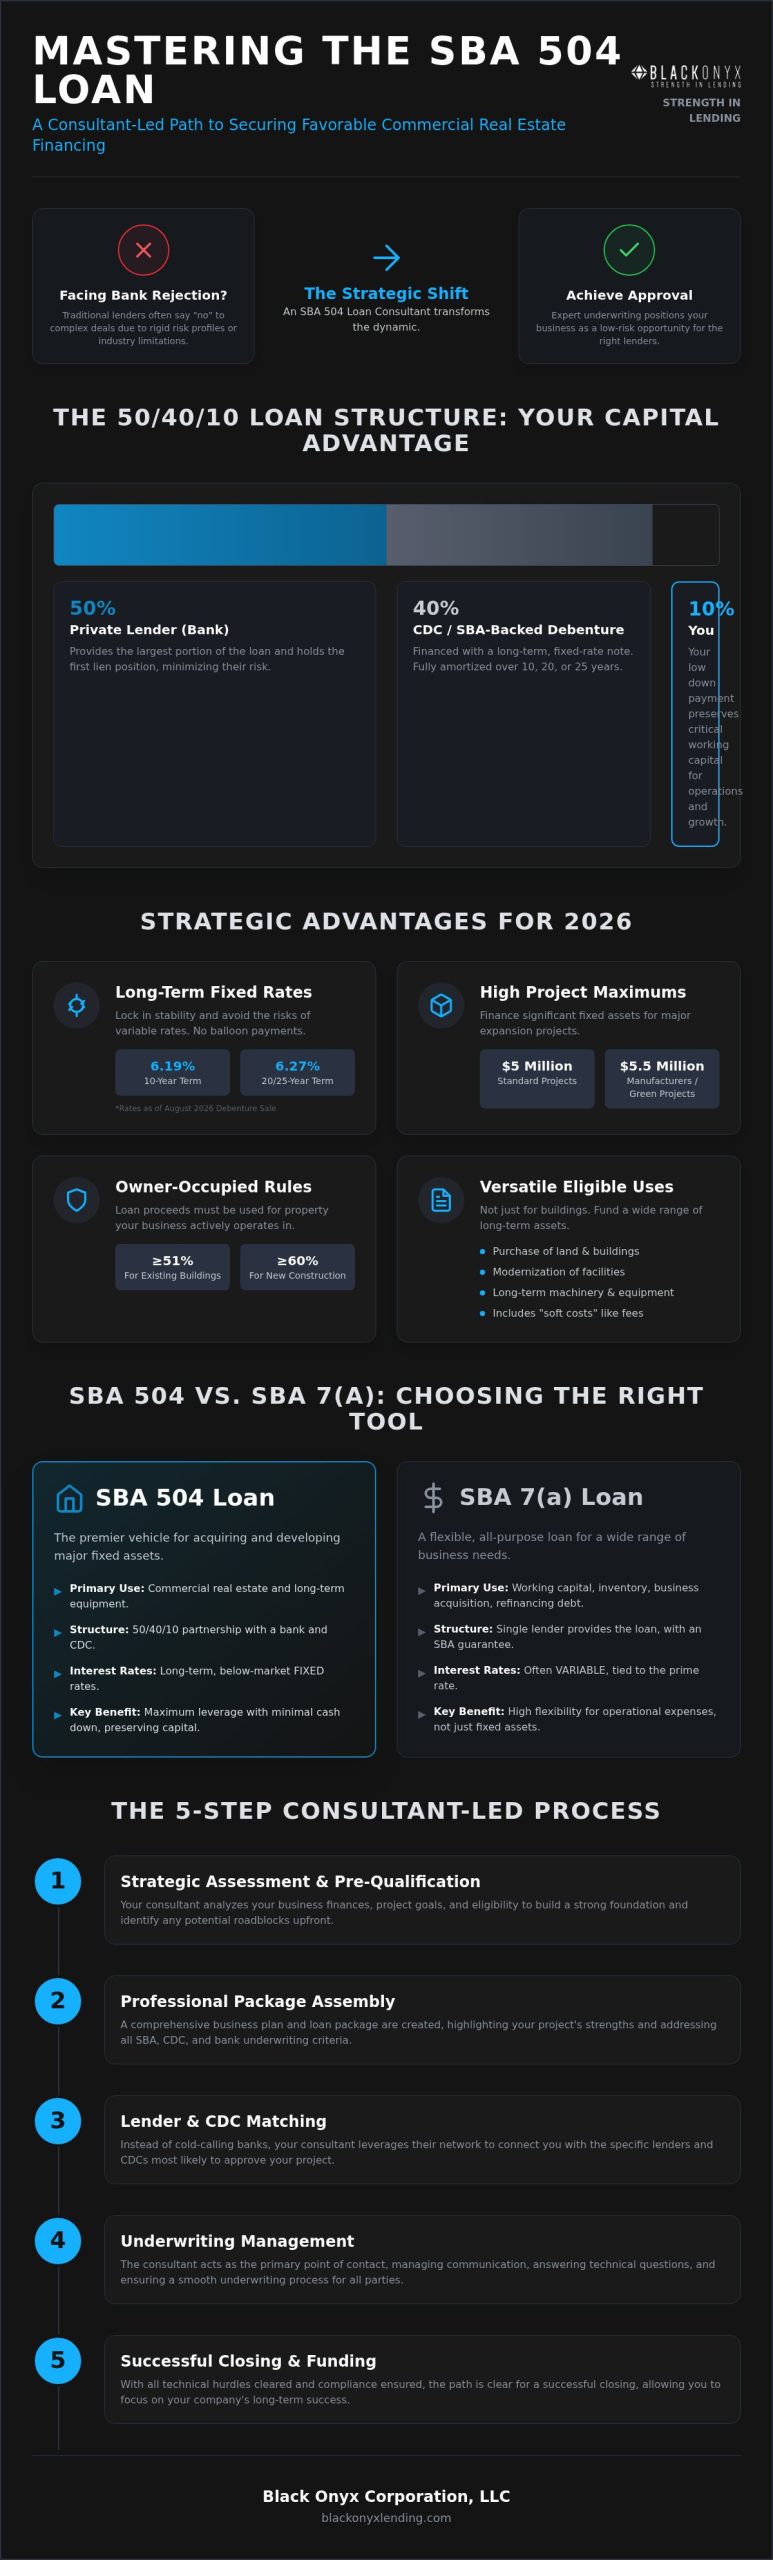
The power of this program lies in its unique tripartite structure. According to the SBA 504 Loan program overview, the financing is split to maximize leverage for the small business owner. A private lender, typically a bank, provides 50% of the project cost and maintains the first lien position. The CDC provides an SBA-backed debenture for 40%, which is fully amortized over 10, 20, or 25 years. This leaves the borrower with a 10% down payment. For a growing company, this 10% entry point is a massive advantage; it keeps critical working capital inside the business rather than locking it into a building’s equity.
Locking in fixed rates is the primary goal for 2026. With standard project maximums at $5 million, and $5.5 million for manufacturers, the scale of these assets requires long-term stability. A consultant ensures you don’t settle for a variable-rate conventional loan that could jeopardize your cash flow if the economy shifts. They bypass the “no” of a single bank by accessing a broader network of funding sources that understand your specific sector.
Consultant vs. CDC: Understanding the Difference
It’s vital to distinguish between these two roles. A CDC is a non-profit corporation certified by the SBA to deliver financing; they are essentially the lender for the 40% portion. An sba 504 loan consultant, however, is your private underwriter and strategist. They help you vet which CDC and which bank are most likely to approve your specific project based on current portfolio balances and industry preferences. An SBA 504 consultant acts as a strategic intermediary for complex asset financing, ensuring every party’s underwriting criteria are met before the first signature is requested.
The Strategic Advantages of the SBA 504 Program in 2026
Locking in long-term stability is the cornerstone of any sound commercial investment. As of the August 2026 debenture sale, the 504 program continues to offer highly competitive fixed rates, with 10-year terms at 6.19% and both 20 and 25-year terms at 6.27%. These are fully amortizing loans, meaning there are no balloon payments to trigger a refinancing crisis a decade down the road. Working with an sba 504 loan consultant ensures you maximize these benefits by properly timing your application to coincide with favorable market windows.
The program’s owner-occupied requirement is a critical eligibility factor. To qualify under official SBA 504 loan guidelines, your business must occupy at least 51% of an existing building. If you’re pursuing new construction, that requirement increases to 60% initially. These rules align with public policy goals like job creation and energy efficiency. For fiscal year 2026, manufacturers and “green” projects enjoy even greater incentives, including loan caps increased to $5.5 million and significant fee waivers. If your project reduces energy consumption or incorporates renewable energy, your consultant can help you leverage these expanded limits to fund a larger footprint.
Commercial Real Estate and Heavy Equipment Uses
The 504 program isn’t limited to just bricks and mortar. You can utilize this financing for the purchase of land, the modernization of existing facilities, or the acquisition of long-term machinery with a useful life of at least 10 years. In 2026, many manufacturers are using these funds to upgrade to automated systems that meet modern efficiency standards. A strategic sba 504 loan consultant can even help you fold “soft costs” like architectural fees, environmental studies, and certain furniture or fixtures into the total project cost, reducing your out-of-pocket expenses at closing.
Preserving Working Capital for Growth
Conventional commercial loans typically require a 25% to 30% down payment, which can drain a company’s cash reserves. The 504 program’s 10% down payment structure is a transformative tool for growth. If you keep more cash in your business, you can fund inventory, hire key personnel, or invest in marketing. As you scale, you might find that accounts receivable financing provides the liquidity needed to bridge the gap between project completion and revenue growth. Partnering with an expert can transform your balance sheet. Explore how a professional sba 504 loan consultant can help you leverage these benefits today.
SBA 504 vs. SBA 7(a): Which Path Should a Consultant Recommend?
High-stakes financial decisions require more than a cursory glance at a brochure. While both programs offer federal backing, an sba 504 loan consultant views them as distinct tools for specific growth phases. The 7(a) program is the “Swiss Army knife” of business debt, ideal for working capital, business acquisitions, or debt refinancing. However, it often carries variable interest rates that can reach 13.25% in late 2026. In contrast, the SBA 504 loan program is a dedicated vehicle for fixed assets, offering the security of long-term fixed rates that protect your margins from market volatility. If your goal is to own your facility rather than rent it, the 504 is the superior strategic choice. Understanding the full spectrum of types of business loans for small business available in 2026 can help you determine which financing vehicle best aligns with your growth objectives.
When 504 is the Clear Winner
If your project involves heavy manufacturing equipment or large-scale real estate, the 504 is almost always the correct path. It allows for a combined loan limit of up to $10 million when paired with a 7(a) loan, a major policy shift effective July 2026. This decoupling of limits means you can now finance $5 million in working capital via 7(a) while simultaneously funding a $5 million real estate project through the 504 program. For a deeper dive into these updates, see our 2026 SBA Loans Strategic Guide. A consultant might even recommend a “7(a) bridge loan” to secure a property quickly while the more complex 504 debenture is being processed. This prevents you from losing a competitive asset to a cash buyer while you wait for the permanent, fixed-rate financing to fund.
The Hidden Costs: Fees and Closing Complexities
Transparency regarding fees is essential for accurate budgeting. The 504 program involves several upfront costs, including a 0.5% guarantee fee and a 1.5% CDC processing fee on the debenture portion. While these closing costs are sometimes higher than conventional financing, the total interest expense over 25 years is significantly lower. Your sba 504 loan consultant acts as a negotiator, often pressuring the primary bank to lower their origination fees to offset these SBA-mandated costs. If you’re a manufacturer, many of these fees are waived in 2026, a detail that can save your business thousands of dollars. This strategic positioning ensures the total project cost remains manageable without sacrificing the benefit of a 10% down payment.
How to Prepare for an SBA 504 Loan: A 5-Step Consultant-Led Process
Securing a multi-million dollar asset requires more than a simple application; it demands a tactical roadmap. Most businesses fail not because of their financial health, but because of poor presentation. An sba 504 loan consultant ensures your file is bulletproof before it reaches a lender’s desk, transforming a daunting bureaucratic hurdle into a streamlined path toward ownership. This process is structured to remove friction and build momentum from the first day of engagement.
- Step 1: Preliminary Underwriting. We perform a deep dive into your credit, cash flow, and global debt service coverage to identify potential deal-breakers early.
- Step 2: Professional Business Planning. We create a compelling narrative that proves job creation or retention, which is essential for SBA compliance.
- Step 3: Sourcing the Senior Lender. Your project is matched with a bank from a network of over 100 funding sources, ensuring you get the most favorable terms for the 50% bank portion.
- Step 4: CDC Submission. We manage the 40% debenture application with the Certified Development Company, handling all technical queries.
- Step 5: Closing and Funding. Our team coordinates the complex logistics between two sets of attorneys and lenders to ensure a smooth transition to ownership.
The Importance of Professional Underwriting
Getting “loan ready” is far more critical than the act of applying itself. If you submit a file with unresolved red flags in your tax returns, you risk an immediate rejection that can follow you to other lenders. Professional underwriting allows us to address cash flow inconsistencies or debt issues before the bank sees them. Some industry professionals report that this proactive preparation can reduce total approval times by as much as 30% by eliminating the typical back and forth between the lender and the borrower. It’s about precision and anticipating the bank’s needs before they ask. For a broader perspective on navigating the commercial loan approval process in 2026, including how digital-first strategies can slash approval times, our strategic business guide offers additional frameworks that complement your 504 preparation.
Document Checklist for 2026 Applicants
Precision in documentation is non-negotiable. To keep the process moving, you must have your records organized and ready for review. The standard 2026 requirements include three years of business and personal tax returns, a current Personal Financial Statement (SBA Form 413), and detailed project cost estimates. If you’re purchasing a building, you’ll also need real estate appraisals and environmental reports. Having these items prepared allows your sba 504 loan consultant to act quickly when a market opportunity arises. Don’t let a missing document stall your growth. You can start the process today by visiting blackonyxlending.com to speak with a strategic advisor.
Why Black Onyx is Your Strategic SBA 504 Partner
Selecting a financial partner is a decision that defines your company’s growth trajectory. At Black Onyx, we don’t just facilitate transactions; we act as a strategic ally that bridges the gap between your vision and institutional capital. While a local bank is limited by its own balance sheet and internal risk policies, an sba 504 loan consultant from our team provides access to a vast ecosystem of resources. We understand that your time is best spent running your operations, not decoding federal regulations. By managing the entire underwriting process, we remove the bureaucratic weight from your shoulders and ensure your project maintains its momentum.
Our expertise spans diverse sectors, from high-precision manufacturing plants to complex medical facilities. We recognize that a manufacturing project might require a higher loan cap of $5.5 million or specific fee waivers available in 2026. If your expansion requires more than just real estate, we build a total capital stack. This often involves integrating your 504 loan with equipment leasing or lines of credit to ensure your business remains liquid after the keys are handed over. We don’t believe in isolated financial products; we believe in comprehensive funding strategies that support your entire balance sheet.
Our Network of 100+ Funding Sources
The primary risk in commercial lending is the “single-source” failure. If your primary bank declines your file, your entire expansion could stall. We mitigate this risk by matching your project with a bank from our network of over 100 funding sources. We also leverage established relationships with CDCs across the United States to find the most efficient processing partners. If your needs extend beyond fixed assets, you can learn about SBA 7a loan brokers to secure working capital for non-real estate requirements. This breadth of choice ensures that we find a lender whose appetite matches your specific industry and credit profile.
Streamlining the Approval Process
Bureaucracy is the enemy of progress. Our proactive approach focuses on identifying and removing obstacles before they trigger a lender’s concern. By performing rigorous preliminary underwriting, we significantly increase the “first-pass” approval rate with both the bank and the CDC. This precision saves weeks of potential delays and protects your reputation with sellers and contractors. When you work with a seasoned sba 504 loan consultant, you aren’t just applying for a loan; you’re executing a calculated strategy for long-term dominance in your market. Contact Black Onyx today for a professional 504 consultation and secure the future of your business assets.
Accelerate Your Path to Asset Ownership
Owning your commercial facility is the most effective way to stabilize long-term occupancy costs and build lasting business equity. By leveraging the 10% down payment structure and 25-year fixed rates, you preserve the working capital essential for scaling your operations. The path to a successful closing requires more than just an application; it demands a strategic narrative built on professional underwriting. Partnering with a seasoned sba 504 loan consultant ensures your project isn’t limited by the narrow criteria of a single local lender.
We provide access to over 100 third-party funding sources and specialized professional underwriting services to bridge the gap between your vision and institutional capital. Our proven track record in Michigan and nationwide means we understand the specific market dynamics that drive your competitive edge. It’s time to move beyond the limitations of traditional financing and secure the assets your business deserves. Secure Your Business Future with an SBA 504 Consultation. Your transformation from tenant to owner starts with a single strategic decision.
Frequently Asked Questions
What is the maximum loan amount for an SBA 504 loan in 2026?
The maximum loan amount for the CDC portion of an SBA 504 project in 2026 is $5 million for standard businesses. If your company is a small manufacturer or is pursuing energy-efficient “green” projects, this limit increases to $5.5 million. It’s important to understand that these caps apply only to the SBA-backed debenture. The total project size can be significantly larger when combined with the 50% private bank contribution and your 10% equity.
Can I use an SBA 504 loan to refinance existing commercial mortgage debt?
Yes, you can utilize the SBA 504 program to refinance existing commercial mortgage debt, provided the debt was used for eligible fixed assets. The refinancing program allows businesses to lock in long-term fixed rates and potentially extract equity for eligible business expenses. An sba 504 loan consultant can help you determine if your current debt meets the “qualified debt” criteria, which typically requires the debt to be at least six months old and current on all payments.
How long does it typically take to close an SBA 504 loan with a consultant?
Closing an SBA 504 loan typically takes between 60 and 90 days. While the federal nature of the program involves multiple parties, working with a consultant can streamline the process by ensuring all documentation is accurate before the first submission. By handling the preliminary underwriting and lender negotiations, our team often reduces the total processing time by approximately 30% compared to applicants who attempt to manage the complex bureaucratic requirements without professional guidance.
What are the job creation requirements for an SBA 504 loan?
Standard SBA 504 guidelines require projects to create or retain one job for every $95,000 of the SBA debenture. For small manufacturers, this requirement is more flexible, at one job per $185,000. If your project doesn’t meet these specific headcount targets, you may still qualify by meeting public policy goals. These include modernizing manufacturing, promoting rural development, or implementing energy-efficient upgrades that reduce consumption by at least 10% to meet 2026 environmental standards.
Is a 10% down payment always available for every business type?
While the 10% down payment is the program’s hallmark, it isn’t universal for every scenario. If your business is a startup with less than two years of operation or if the property is considered “special-purpose,” such as a hotel or gas station, the requirement typically increases to 15%. If both conditions apply, you may be required to provide a 20% down payment. We help you assess these variables during the preliminary underwriting phase to avoid surprises during the approval process.
Can I use an SBA 504 loan for a multi-tenant building if my business is one of the tenants?
You can absolutely use an SBA 504 loan for a multi-tenant building, provided your business meets the occupancy requirements. For existing buildings, your business must occupy at least 51% of the total square footage. If you’re constructing a new facility, you must occupy 60% immediately and have plans to occupy up to 80% eventually. This structure allows you to earn rental income from other tenants while building long-term equity in your primary business location.
What happens if my primary bank rejects the 50% portion of the 504 loan?
If your primary bank rejects the senior 50% portion, your project doesn’t have to stall. A strategic sba 504 loan consultant leverages a national network of over 100 funding sources to find a lender with a higher appetite for your specific industry or credit profile. Banks often have internal limits on certain sectors; if one says no, we pivot to another institution that views your project as a growth opportunity rather than a risk to their portfolio.
Are SBA 504 loan interest rates fixed or variable?
The interest rates for the 40% CDC portion are always fixed for the entire 10, 20, or 25-year term. This provides long-term payment stability that is rare in commercial finance. The 50% bank portion of the loan can be either fixed or variable, depending on the terms negotiated with the private lender. Our role is to negotiate with the senior lender to ensure their portion complements the stability of the SBA debenture and fits your cash flow needs.