In 2026, applying for federal funding without a strategic advocate isn’t just risky; it’s often a fast track to an avoidable rejection letter. As the SBA reinstates more rigorous equity requirements and updates its Standard Operating Procedure to version 50 10 8.1, the margin for error has vanished. Partnering with a specialized sba 7a loan broker has transformed from a simple convenience into a vital competitive advantage for growing firms. If you provide a lender with a perfect application the first time, then you eliminate the weeks of back and forth that typically stall business momentum.
It’s frustrating to face opaque underwriting requirements and slow approval timelines at traditional banks that don’t seem to value your time. You deserve a process that respects your professional urgency and recognizes the unique strengths of your business model. This 2026 guide demonstrates how a strategic bridge can navigate federal complexities to secure capital with better terms and higher approval rates. We will break down the latest interest rate caps, new ownership citizenship rules, and the exact steps to move from a state of limitation to one of significant opportunity.
Key Takeaways
- Learn why a specialized sba 7a loan broker is essential in 2026 to bypass the “one bank” trap and access a broader range of credit committees.
- Discover how professional pre-underwriting identifies potential red flags before they reach a lender, significantly increasing your chances of a first-time approval.
- Understand the impact of 2026 interest rate caps and the latest SBA Standard Operating Procedure updates on your total borrowing capacity.
- Identify the exact “pivot point” when traditional financing is no longer viable and a strategic SBA bridge becomes the most effective path forward.
- Explore how leveraging a network of over 100 third-party funding sources removes bureaucratic obstacles and accelerates your business momentum.
What is an SBA 7a Loan Broker and Why Do You Need One?
An sba 7a loan broker is a professional intermediary who acts as a strategic bridge between your business and a network of SBA-approved lenders. While the SBA 7(a) loan program provides the framework for these government-backed loans, the actual application process is notoriously rigid and unforgiving. A broker’s primary role is to match your specific financial profile with the lender most likely to provide an approval with favorable terms.
In 2026, this role has become a necessity rather than a luxury. With the October 1, 2026, implementation of SOP 50 10 8.1, the SBA has reinstated more stringent underwriting rules that require a higher level of precision. If you attempt to navigate these updates alone, then you risk falling victim to the latest credit tightening trends. A broker ensures your file meets these new, rigorous standards before it ever hits a lender’s desk. They act as your primary advocate throughout the 2026 SBA Loans: A Strategic Guide for Business Growth.
You might see automated “Lender Match” tools online, but don’t be misled by the promise of instant digital pairing. These algorithms frequently fail to capture the nuance of non-standard business models or complex acquisition deals. Human underwriting remains the only reliable way to identify “red flags” that trigger immediate rejections in a traditional bank setting. A seasoned sba 7a loan broker provides the individualized attention necessary to overcome these systemic hurdles.
The Core Responsibilities of an SBA Broker
A broker doesn’t just pass papers; they curate opportunities. They identify specific lender appetites for your industry, ensuring you don’t waste time with institutions that aren’t currently funding your sector. Their core duties include:
- Industry Alignment: Matching your risk profile with lenders who understand your specific market dynamics.
- SOP Compliance: Packaging every document to meet the strict 2026 Standard Operating Procedure requirements.
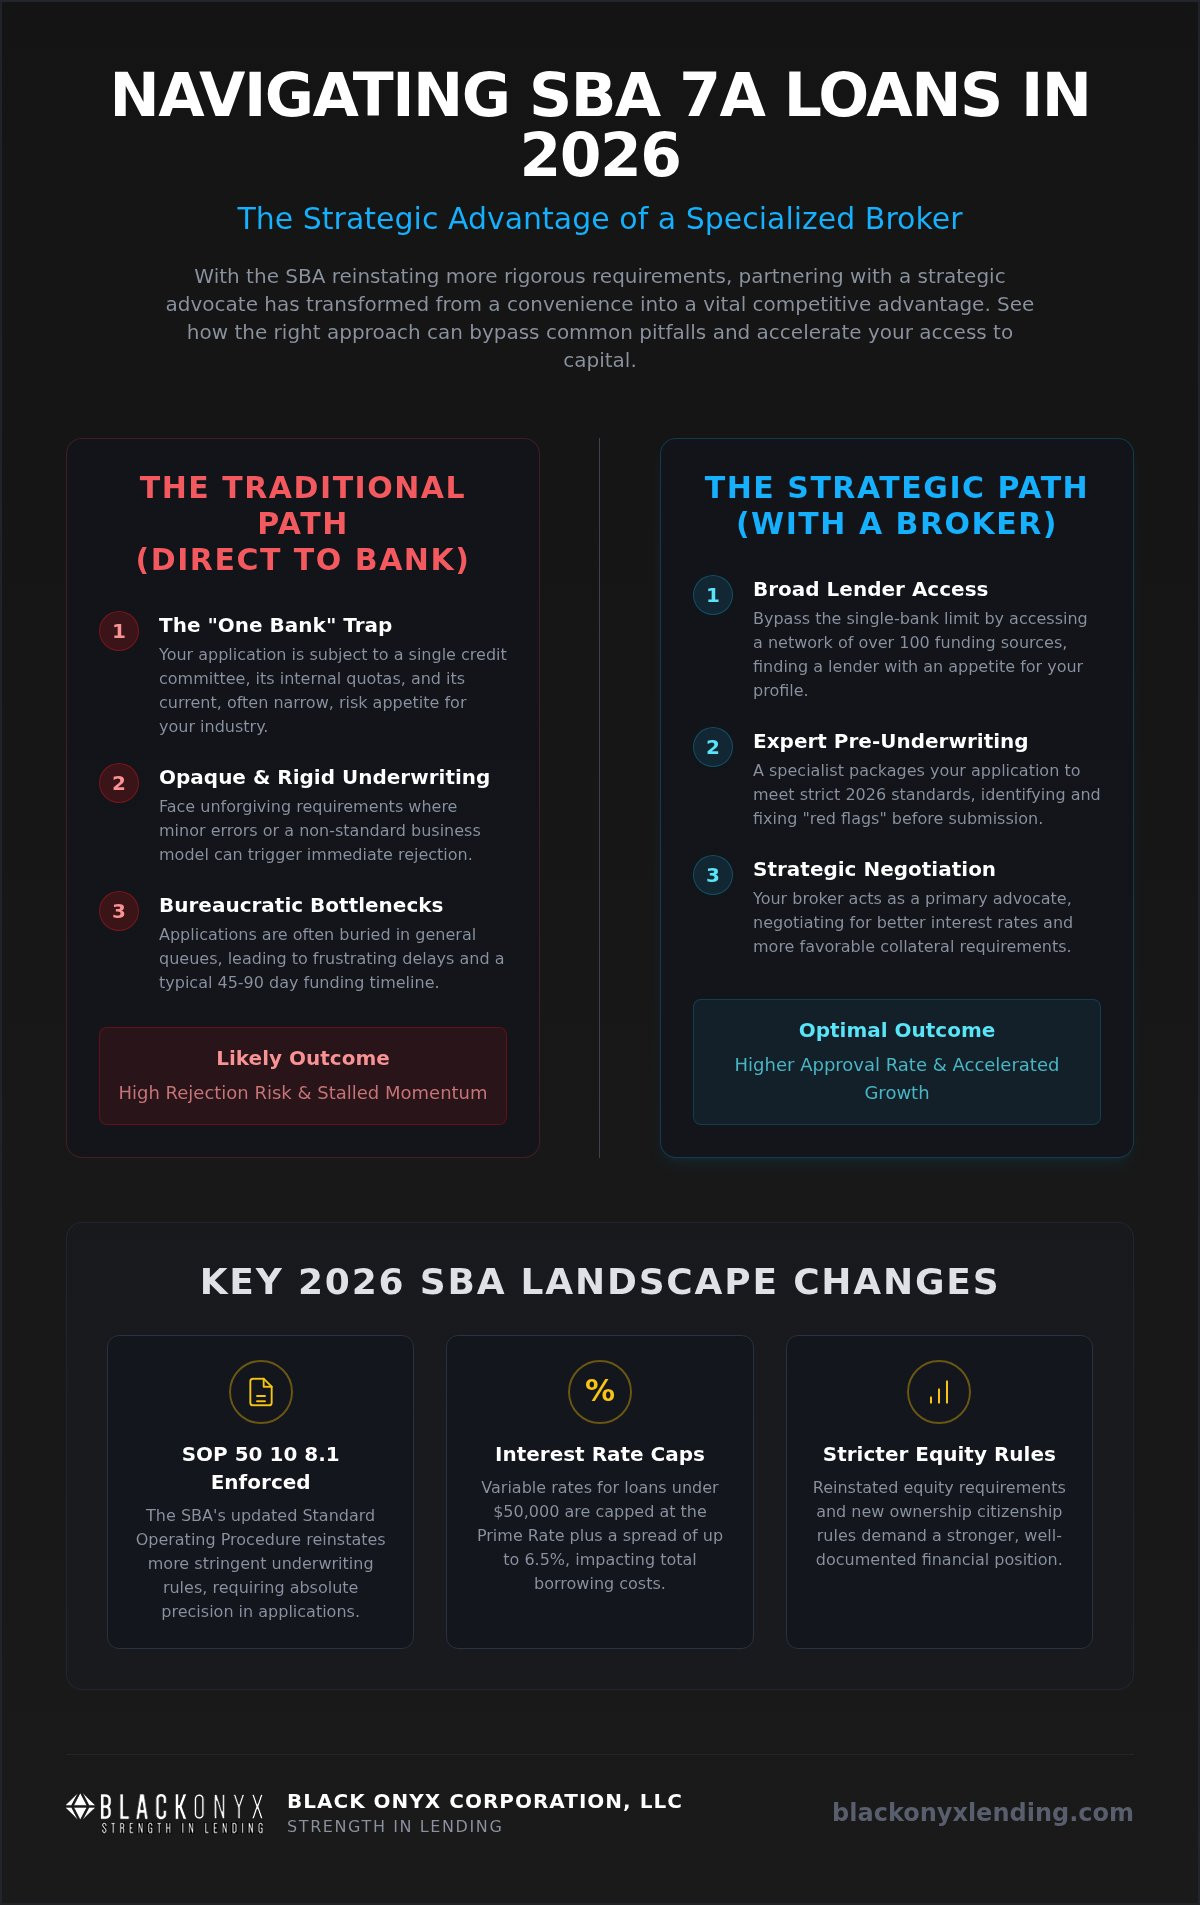
- Direct Negotiation: Advocating for better interest rates and collateral requirements. For example, variable rates are currently capped at the Prime Rate plus a spread of up to 6.5% for loans under $50,000.
Broker vs. Consultant: Understanding the Nuance
Traditional brokers often focus solely on the transaction, while consultants focus on the long-term business plan. Black Onyx combines these roles to ensure “loan readiness.” If your business needs capital for expansion or equipment, then you need a partner who understands both the immediate deal and the global market dynamics. This dual approach ensures you aren’t just getting a loan; you’re building a foundation for a competitive edge. By integrating professional underwriting with strategic consulting, we remove the bureaucratic obstacles that typically stall business momentum.
SBA 7a Loan Broker vs. Direct Bank: The Strategic Advantage
Entering a local bank branch feels like the logical first step for financing. However, this often leads to the “One Bank” trap. If that specific institution has reached its internal quota for your industry or recently tightened its credit policy, then your application is dead on arrival. An sba 7a loan broker removes this limitation by providing a strategic bridge to a vast network of resources. Instead of relying on a single credit committee, you gain access to over 100 third-party funding sources that may have a higher appetite for your specific profile.
Speed of execution is another critical differentiator. Large institutions often bury SBA applications in a general intake queue, contributing to the typical 45 to 90 day funding timeline. Brokers bypass these bureaucratic bottlenecks by working directly with specialized lending departments. They also provide the objective advice that a bank employee cannot. If an SBA loan isn’t your best move, then a professional consultant will tell you. You might find that asset-based financing or equipment leasing offers a more efficient path to your goals.
Lender Appetite and Industry Specialization
Banks frequently shift their lending focus based on internal risk assessments. In 2026, some institutions avoid sectors like manufacturing or specialized healthcare, even if the borrower is financially strong. A broker identifies “Preferred Lenders” who are actively seeking your business type. They understand how geographic location impacts lending decisions and match you with a source that has a demonstrated appetite for your region. This ensures your application lands on the desk of a lender already predisposed to say yes.
Efficiency and the ‘First-Time Right’ Principle
Application fatigue is a real threat to business momentum. Submitting multiple unpolished applications can lead to a permanent “decline” on your SBA record, which other lenders can see. An sba 7a loan broker ensures you are “first-time right” by submitting a file that already adheres to the SBA lender guidelines. This precision streamlines communication between you, the bank, and the SBA. By identifying red flags before the bank sees them, a broker moves you from a state of limitation to one of significant opportunity without the typical delays of traditional institutions.
The Underwriting Advantage: How Brokers Streamline Approvals
Underwriting is the most common point of failure for SBA 7a loans. Traditional banks view this process as a final hurdle to clear, but an sba 7a loan broker treats it as the foundation of the entire strategy. If you submit a file without professional pre-underwriting, then you’re essentially guessing what the credit committee wants to see. A broker identifies “red flags” like inconsistent tax returns or insufficient collateral before the bank ever opens the folder. This proactive approach transforms the underwriting phase from a gatekeeping function into a consulting service that prepares your business for success.
Addressing the cost of professional assistance is essential for any savvy business owner. While some view broker fees as an additional expense, they are actually a strategic investment in the final result. If a direct-to-bank application fails, then the hidden costs of lost time and missed market opportunities can be devastating. A broker delivers the precision needed to secure capital on the first attempt, ensuring your momentum remains uninterrupted. Understanding the full commercial loan approval process can help you anticipate each stage and prepare your documentation accordingly.
Professional Underwriting Consulting
Effective underwriting requires a deep analysis of your Debt Service Coverage Ratio (DSCR) from a lender’s perspective. If your financials don’t reflect true cash flow, then a broker helps clean up statements to highlight legitimate add-backs. This process ensures your “Use of Proceeds” statement is airtight and aligns with current market realities. For instance, as of June 1, 2025, the SBA requires a minimum equity injection of 10% for start-ups. An sba 7a loan broker ensures your capital structure meets this requirement before submission, using professional business planning to justify every dollar requested.
Managing Systemic Hurdles and Bureaucracy
The SBA’s 2026 update to SOP 50 10 8.1 has introduced more rigorous insurance requirements and specific rules for business acquisitions. Navigating these systemic hurdles requires a partner who understands the nuance of “character” assessments and personal guarantee concerns. Brokers act as a strategic bridge, translating the needs of an entrepreneur into the rigid language of a bank officer. This reduces the friction that often leads to approval delays. By bridging the communication gap, they move you from a state of limitation to one of significant opportunity.
Navigating the 2026 SBA Landscape: When to Engage a Consultant
The 2026 financial environment demands more than just a passing knowledge of federal programs. Interest rate fluctuations have direct consequences on your borrowing power. As of September 2026, the maximum variable interest rate for loans exceeding $350,000 is capped at 9.75 percent. If you’re managing a high-growth firm, then you need an sba 7a loan broker who understands how these caps influence your long-term debt service and total cost of capital.
Identifying the “pivot point” is crucial for maintaining your competitive edge. This is the moment when traditional bank financing fails to meet your needs due to rigid collateral requirements or industry-wide credit tightening. If your local branch says no, then it’s time to engage an sba 7a loan broker who can pivot your strategy toward government-backed solutions. In some cases, a broker might suggest The Strategic Guide to Commercial Equipment Leasing in 2026 as a more efficient way to preserve working capital while still acquiring the assets you need. For businesses pursuing commercial property, working with an sba 504 loan consultant can provide a complementary path to financing owner-occupied real estate with favorable long-term terms.
Success requires a significant lead time. Starting the process six months before you need the funds is a strategic necessity. This buffer allows for the meticulous preparation of the Quality of Earnings reports now required for larger acquisition deals under the October 2026 SOP updates. If you wait until the need is urgent, then you risk falling victim to the 45 to 90 day funding timelines that characterize the current market.
Strategic Growth and Expansion Planning
The SBA 7a program remains a powerhouse for business acquisitions. However, the latest SOP 50 10 8.1 update introduces more institutionalized rules, including higher debt service coverage ratios for certain deals. A broker helps you leverage these funds alongside “Section 179” tax benefits to maximize your return on investment. If you’re planning multi-stage funding for rapid growth, then a strategic ally ensures each phase of capital injection supports your long-term objectives without creating a state of limitation.
Global Resources for Local Businesses
Based in Troy, Michigan, Black Onyx acts as a strategic bridge for local firms to reach national and international markets. A global network provides more stability than a local credit union because it offers a vast range of options during regional economic shifts. If you need cross-border financing or specialized medical finance, then we connect you to over 100 third-party funding sources. To secure the best possible terms for your expansion, connect with our strategic underwriting team today.
Partnering with Black Onyx: Your Bridge to Global Funding Sources
Black Onyx Corporation, LLC operates as more than a standard sba 7a loan broker; we are a strategic partner dedicated to your long term success. While traditional lenders often present a series of bureaucratic obstacles, our team focuses on removing those hurdles to foster immediate momentum. We provide a strategic bridge to over one hundred third party funding sources, ensuring that your business is never limited by the narrow credit policies of a single institution. If you choose to partner with us, then you gain access to a global network of resources that traditional banks simply cannot match.
Our results oriented approach transforms your balance sheet by moving your business from a state of limitation to one of significant opportunity. We don’t just facilitate transactions. We provide the professional underwriting and commercial lender negotiation required to streamline the SBA approval process. This commitment to highly individualized attention ensures that your specific needs are met with precision and speed. By bypassing the general intake queues of major banks, we respect your time and accelerate your path to capital.
Our Specialized Consulting Framework
We utilize a rigorous underwriting and negotiation framework to prepare your file for the 2026 credit market. If your financial statements are complex, then our team applies professional underwriting to reflect your true cash flow and potential. This “If-Then” logical approach simplifies your financial decision-making by providing clear, actionable insights. In a world of automated lending and impersonal algorithms, the value of an sba 7a loan broker who understands your specific industry appetite is immeasurable. We identify the strategic alternatives that best suit your growth trajectory, ensuring your capital structure is built for resilience.
Securing Your Competitive Edge
In the current 2026 landscape, proactive and decisive action is the only way to maintain a competitive edge. Black Onyx acts as a powerful ally, positioning your firm as a top-tier candidate for funding. We understand that time is a critical resource for busy professionals. We get to the core of your financing needs quickly, breaking down complex concepts into digestible insights. If you are ready to move from a state of limitation to one of progress, then the next step is a comprehensive assessment of your business plan. Contact Black Onyx for a consultation and begin your strategic underwriting assessment today.
Secure Your Business Future with Strategic Capital
Navigating the 2026 federal lending landscape requires more than just a strong business model; it demands a precise, strategic approach to underwriting and negotiation. If you don’t have a specialized advocate, then you risk stalling your growth due to rigid institutional quotas and opaque bank requirements. A seasoned sba 7a loan broker acts as a powerful ally, transforming your financial profile and providing a strategic bridge to over 100 third-party funding sources. This proactive methodology ensures you meet the latest SOP 50 10 8.1 requirements while bypassing the bureaucratic bottlenecks that typically lead to rejection.
Black Onyx is committed to removing these obstacles and fostering your long-term momentum. Our experienced underwriting team and proven track record in commercial lender negotiation provide the precision your enterprise deserves. Streamline your SBA 7a approval with a strategic consultation from Black Onyx and move from a state of limitation to one of significant opportunity. Your next phase of growth is within reach.
Frequently Asked Questions
Do SBA 7a loan brokers charge upfront fees for their services?
Black Onyx Corporation, LLC does not charge upfront fees for basic lender matching; however, we do generate revenue through professional consulting fees for specialized underwriting and business planning. Most fees are commissions earned upon the successful closing of your commercial loan. If a firm demands significant payment before providing a specific service, then you should evaluate their transparency. This results-oriented model ensures our team is intensely focused on your ultimate funding success.
What is the difference between an SBA Preferred Lender and an SBA broker?
An SBA Preferred Lender is a bank with the authority to approve loans internally without a secondary review from the federal government. By contrast, an sba 7a loan broker acts as a strategic bridge to a network of over 100 third-party funding sources. While a bank is limited to its own credit committee, a broker provides a vast range of options to find the most favorable market terms for your business.
Can an SBA 7a loan broker help if I have been declined by my bank?
Yes, a broker can often secure funding even after a traditional bank has issued a rejection. Banks often decline applications because they have reached internal limits for a specific industry or geographic region. An sba 7a loan broker analyzes the reasons for the decline and rematches your profile with a lender that has a higher appetite for your business model. This process removes bureaucratic obstacles and restores your momentum.
How much does it cost to hire an SBA loan consultant in 2026?
The total cost varies based on the complexity of your deal and the depth of professional underwriting required. Typically, costs include loan origination fees paid at closing and consulting fees for business planning or lender negotiation. You should view these as a strategic investment in approval. If you secure better terms or a higher approval rate, then the expertise provided by a consultant offers a significant return on investment.
What documents will an SBA 7a broker need to begin my underwriting assessment?
To begin a professional underwriting assessment, you will need to provide several key documents:
- Three years of business and personal tax returns.
- Current year-to-date profit and loss statements and balance sheets.
- A formal Use of Proceeds statement.
- Personal financial statements for all owners with 20 percent stake or more.
Providing these early allows your broker to identify systemic hurdles before the bank sees your file.
How long does the SBA 7a approval process take when working with a broker?
The typical timeline for funding ranges from 45 to 90 days from the start of the application. While federal review times are outside of our control, working with a broker accelerates the process by ensuring your file is first-time right. If your application is professionally packaged, then you avoid the common delays caused by missing information or confusing paperwork. This efficiency respects the time of busy professionals.
Can a broker help me secure an SBA 7a loan for a business acquisition?
Yes, securing capital for business acquisitions is a primary function of this program. The 2026 SOP 50 10 8.1 updates have introduced more specific rules for acquisitions, including higher debt service coverage requirements for certain deals. A broker helps you navigate these new institutionalized rules and manages the requirement for Quality of Earnings reports. This strategic support ensures you maintain a competitive edge during the ownership transition.
Is it possible to use an SBA 7a loan for equipment leasing and working capital simultaneously?
It is possible to fund both equipment and working capital within a single loan package. The 7a program is highly versatile; it allows you to consolidate various needs into one structured facility. If your requirements are extensive, then a broker might suggest a hybrid strategy. This could involve combining an SBA loan for long-term debt with equipment leasing to preserve your cash flow and move your business toward significant opportunity.